
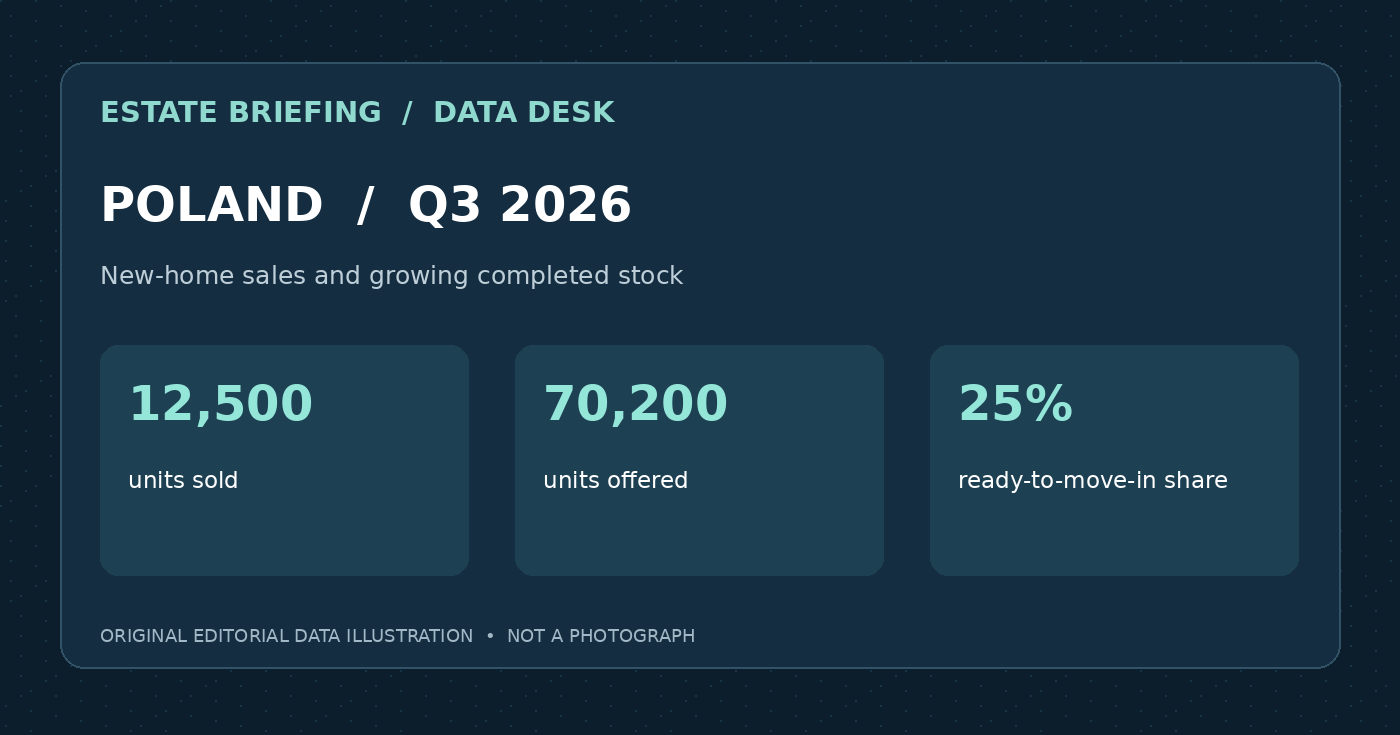
Poland’s seven largest primary housing markets recorded 12,500 developer sales in the third quarter of 2026, according to figures attributed to JLL. Developers introduced about 12,800 homes during the same period. The two flows were close, but the available stock remained substantial at 70,200 units at the end of September. These are monitored primary-market units, not every housing transaction in Poland.
The number of completed homes still awaiting sale matters particularly for buyers. Finished apartments represented 25% of the offer, compared with 16% a year earlier, according to JLL figures reported by EurobuildCEE. That is a very different negotiation setting from a market dominated by off-plan inventory. September sales totalled about 4,400 apartments, including around 1,400 in Warsaw.
The aggregate also hides local differences. Warsaw’s offer is closer to current demand than inventories in Łódź and Katowice, where absorption would take much longer at the recent pace. Buyers should compare finished units, delivery dates and developer incentives in the particular city rather than assume a nationwide shortage. Reported offer prices are not agreed final contract prices, and a sales rebound does not automatically imply a rise in valuations.
Sources and limits
EurobuildCEE reporting JLL residential research ↗
Industry report · 2026-10-13
ISBnews reporting JLL figures ↗
News agency report · 2026-10-13
JLL Residential Market in Poland Q2 2026 ↗
Market research baseline · 2026-07-15
This is research, not investment, tax or legal advice. Definitions and observation dates remain attached to every claim.