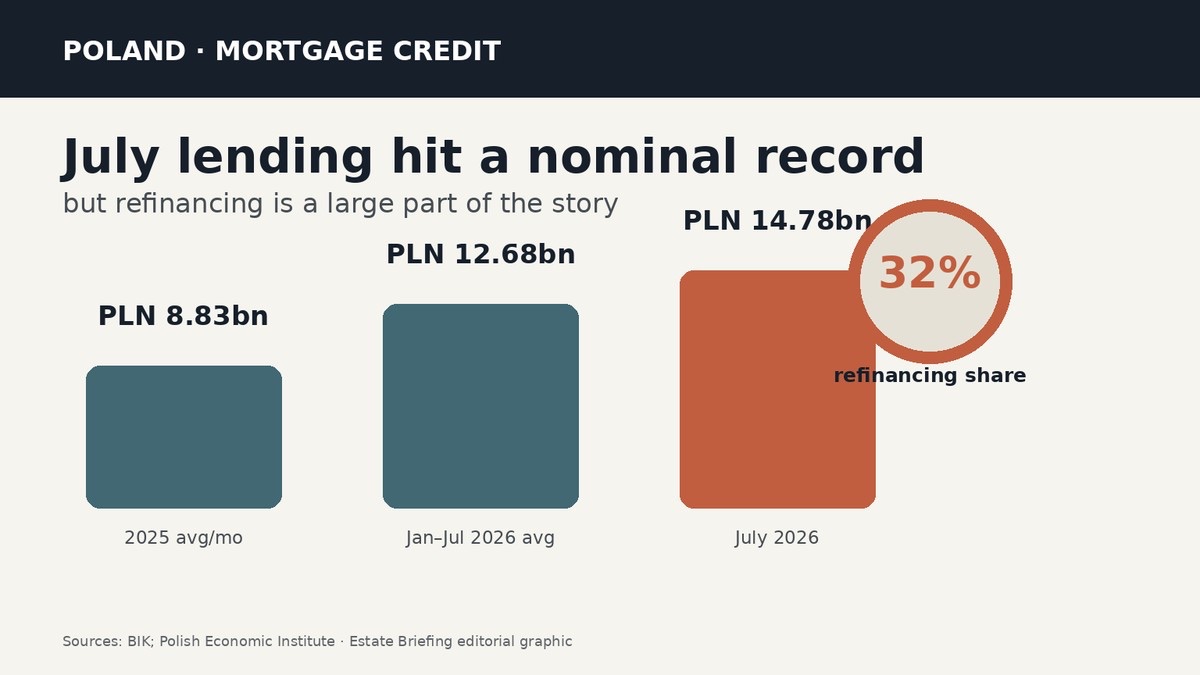
Poland's housing-credit market entered the second half of 2026 at full speed. BIK data for July show banks and credit unions issued 33.1% more housing loans than in July 2025, while the value of lending jumped 45.3%. The Polish Economic Institute puts the month's total at PLN 14.78 billion, the highest nominal monthly reading in the series it cites.
That headline needs one important qualifier: refinancing is doing unusually heavy work. PIE estimates that 32% of new housing lending in July was refinancing. In other words, a meaningful part of the record reflects households replacing existing debt, not buyers adding an equivalent number of homes to transaction demand.
The underlying demand is still strong. BIK's July demand index was 22.0% higher year on year, the number of applicants was up 11.6%, and the average requested loan reached PLN 538,500, 9.3% above a year earlier. Actual new housing loans averaged PLN 487,530, up 9.1% year on year according to PIE.
The scale of the rebound is easier to see over several months. From January through July 2026, the value of housing loans granted was 57.2% higher than in the same period of 2025. PIE calculates that PLN 88.78 billion was already lent in the first seven months, almost matching the PLN 88.69 billion full-year record from 2021 and putting 2026 on course to exceed 2025's PLN 105.9 billion total if the pace holds.
For the housing market, the composition matters more than the record label. Refinancing can improve household cash flow and reduce debt-service costs without creating a property transaction. New purchase mortgages, by contrast, feed directly into effective demand for homes. A market report that treats every refinanced złoty as fresh buying power would overstate the immediate support for sales volumes.
The next useful signal is therefore not simply another lending record. It is whether the share of purchase financing remains strong after separating refinancing, and whether lower borrowing costs translate into more signed housing transactions rather than mainly better terms for existing borrowers. Estate Briefing will keep those two channels separate when comparing credit growth with prices and transaction volumes.
Sources and limits
BIK ↗
Credit bureau data · 2026-08-25
BIK ↗
Credit demand data · 2026-08-18
Polish Economic Institute ↗
Institutional research · 2026-09-04
This is research, not investment, tax or legal advice. Definitions and observation dates remain attached to every claim.