
Georgia has lengthened a specific transitional value-added-tax arrangement connected with immovable property. In a notice dated 19 October 2026, the Revenue Service said an amendment effective 16 October changed the relevant end date from 1 January 2029 to 1 January 2033. The cited provisions are Article 309, paragraphs 79 and 81², of the Tax Code. The announcement concerns an exemption with the right of deduction for qualifying property supplies and associated construction and installation services.
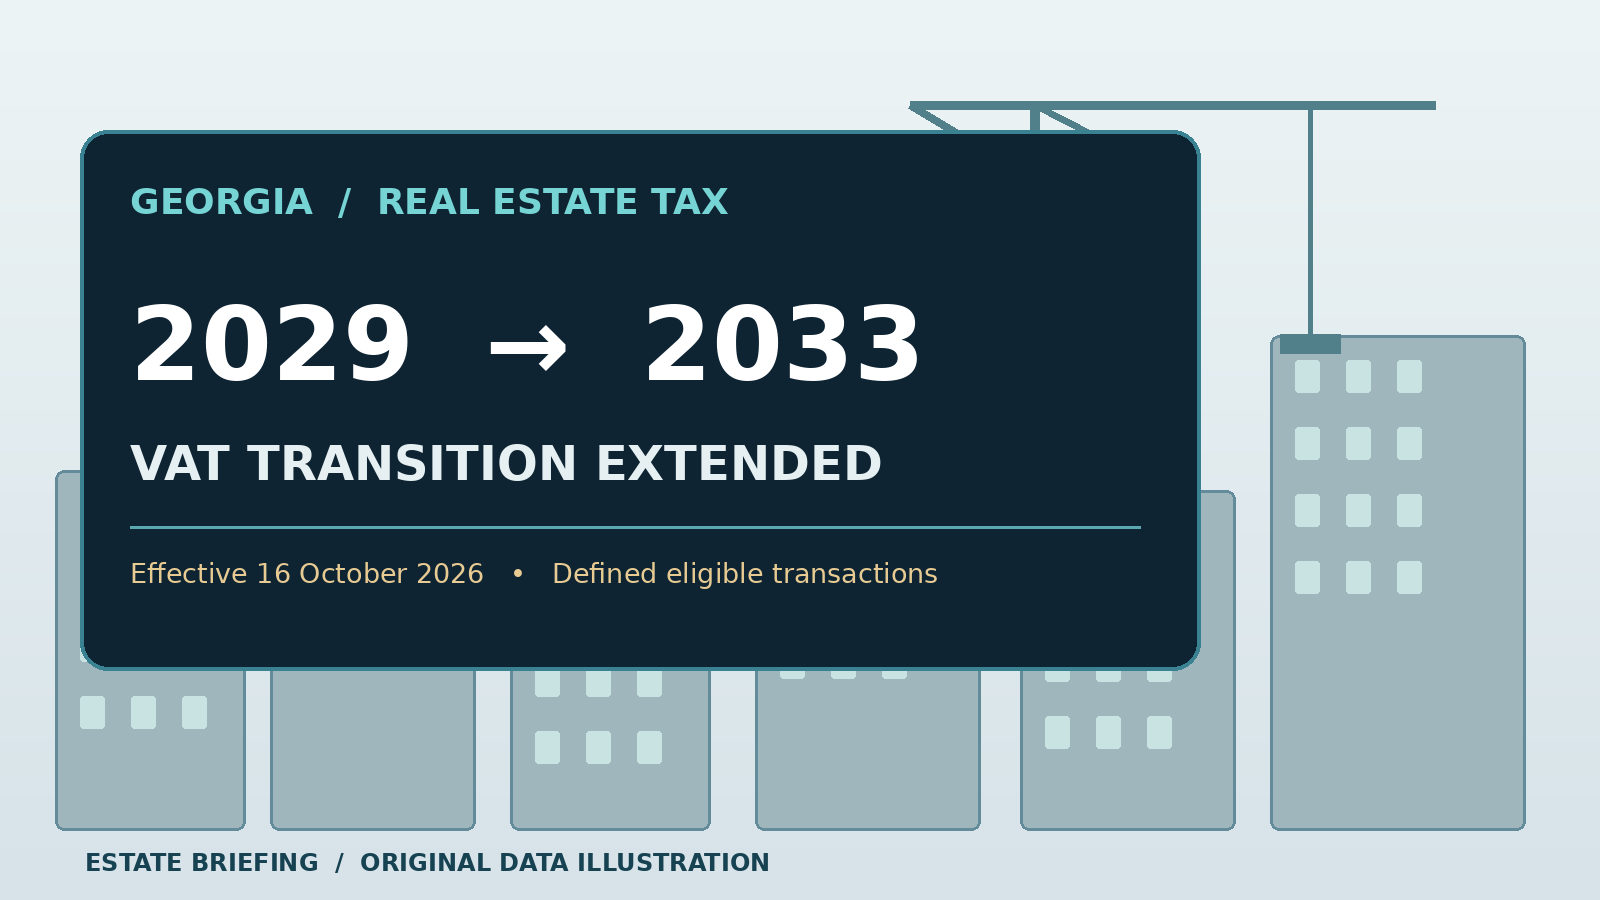
The four-year extension matters to developers and counterparties assessing the tax treatment of projects that fall within those transitional provisions. However, the notice does not say that every new apartment is exempt from VAT, that all construction costs become tax-free, or that a project may legally delay completion until 2033. Eligibility must be checked against the actual transaction, the operative tax-code language and the documents of the specific development.
For buyers, the practical question is what the written price includes. A quoted unit price, a construction-stage instalment schedule and the VAT treatment of the supplier are different matters. Ask whether a price is final, whether any tax is separately chargeable and whether the contractual delivery date is independent of the tax transition. Do not assume the tax extension creates an automatic discount.
This is particularly relevant when comparing completed apartments with off-plan property in Batumi. homeradar.ge’s separate comparison of ready and unfinished apartments explains the waiting-period trade-off; its price and rent scenarios are context, not evidence about tax eligibility. Buyers should use the Revenue Service notice for the legal change and obtain transaction-specific tax advice before relying on a preferential regime.
Sources and limits

Revenue Service of Georgia — Tax Code amendment effective 16 October 2026 ↗
Official tax notice · 2026-10-19
This is research, not investment, tax or legal advice. Definitions and observation dates remain attached to every claim.
 Poland · Poland unveils public housing investment map as ministry reports PLN 7.1bn in support
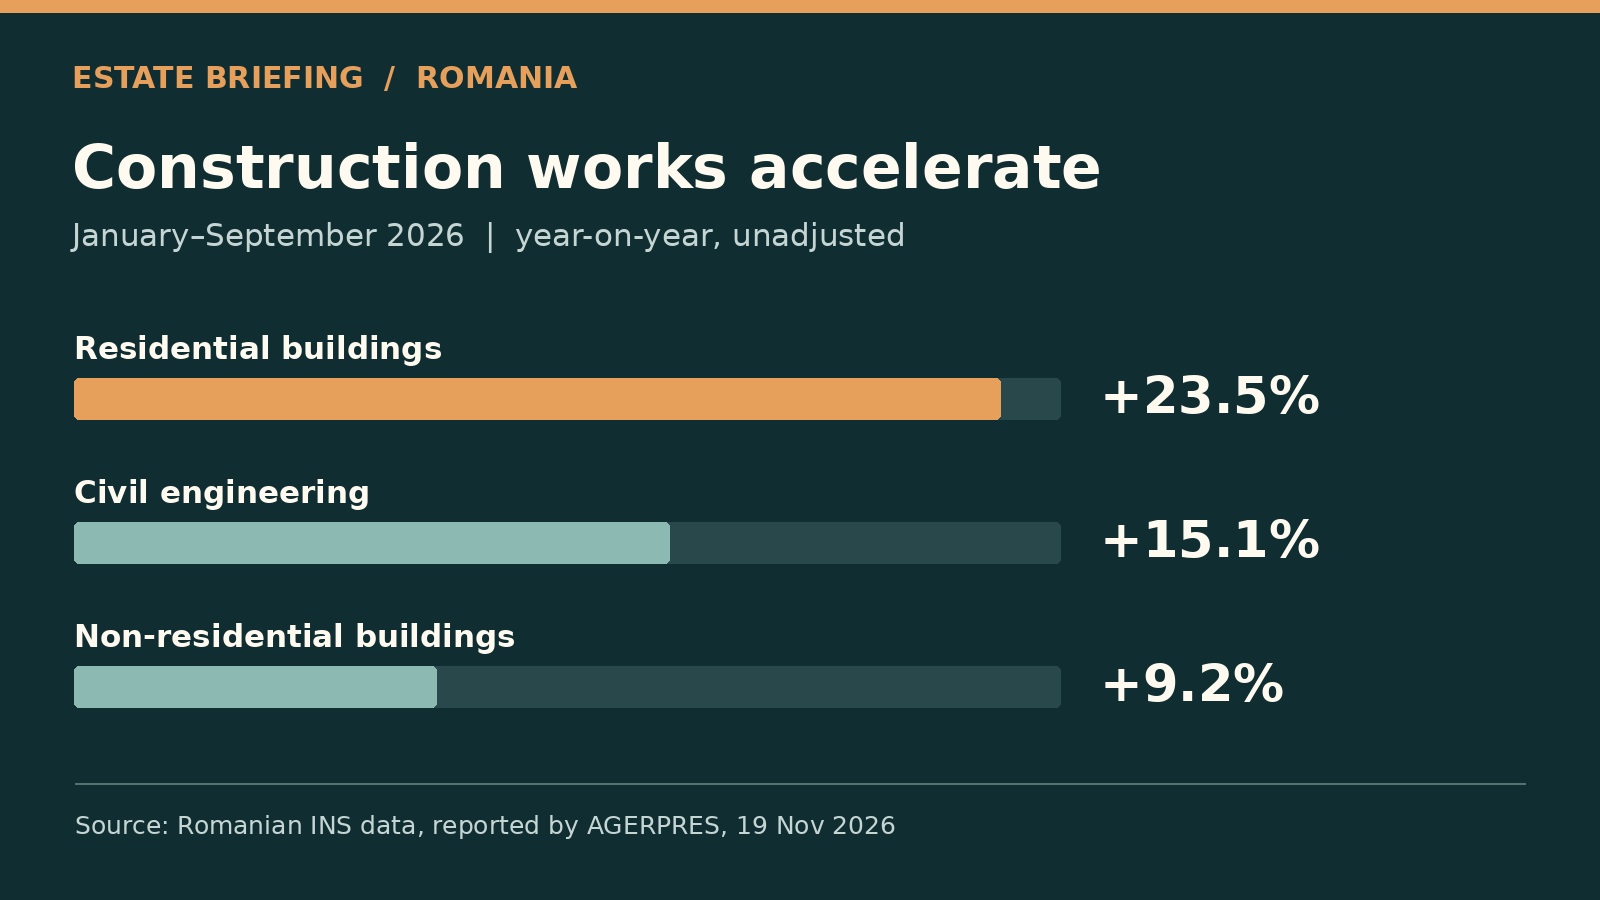 Romania · Romanian residential construction rises 23.5% in nine months
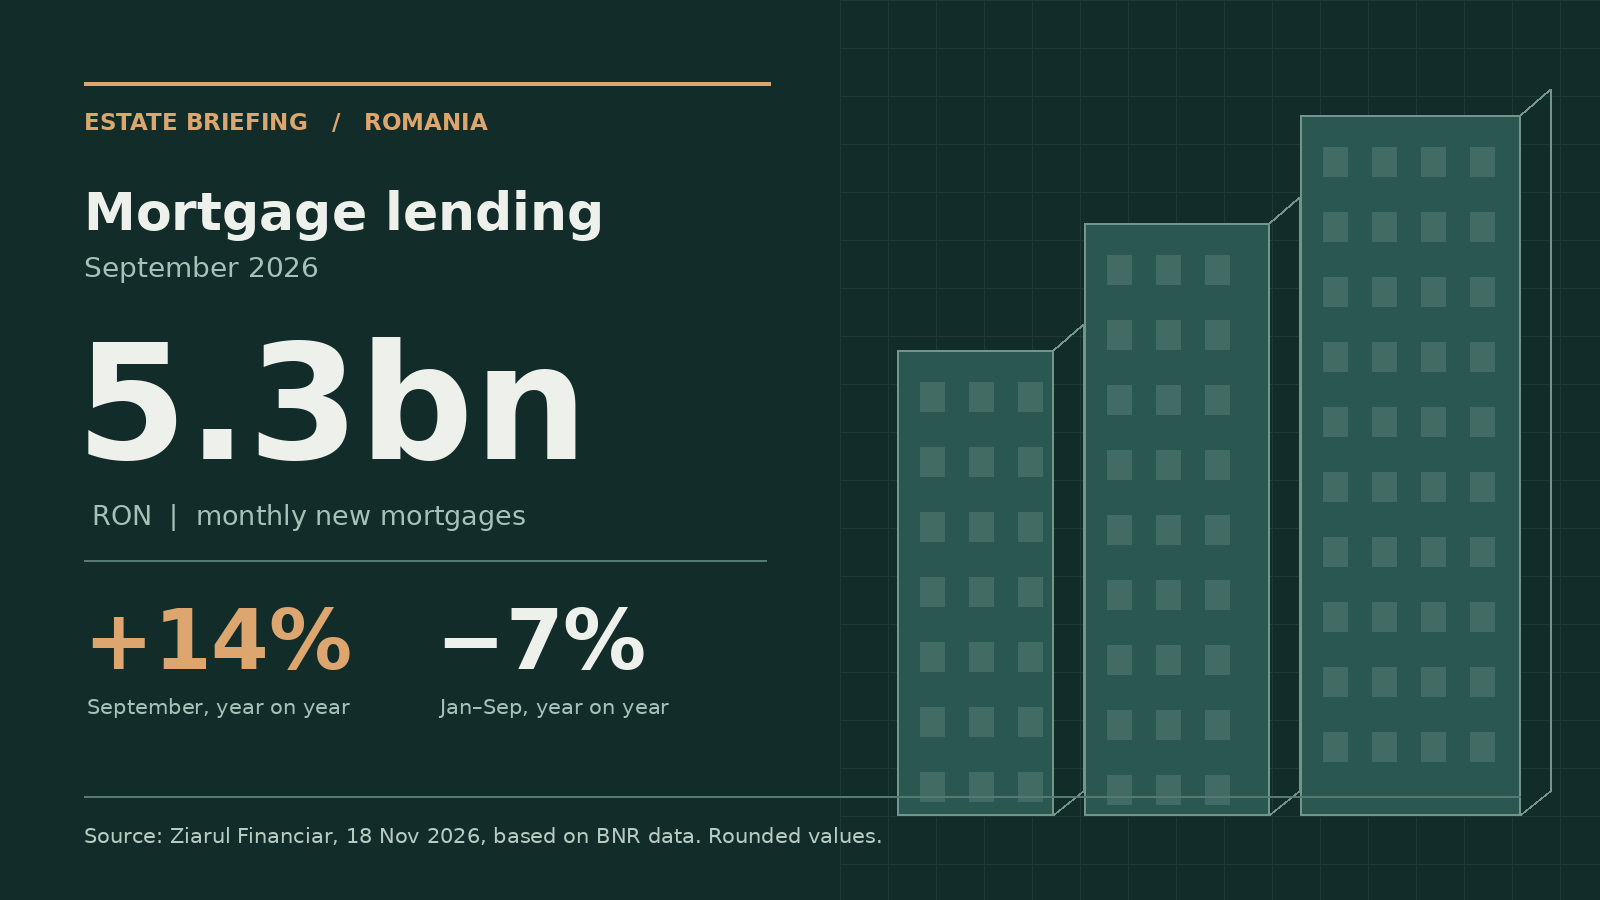 Romania · Romania’s September mortgage lending reaches a record