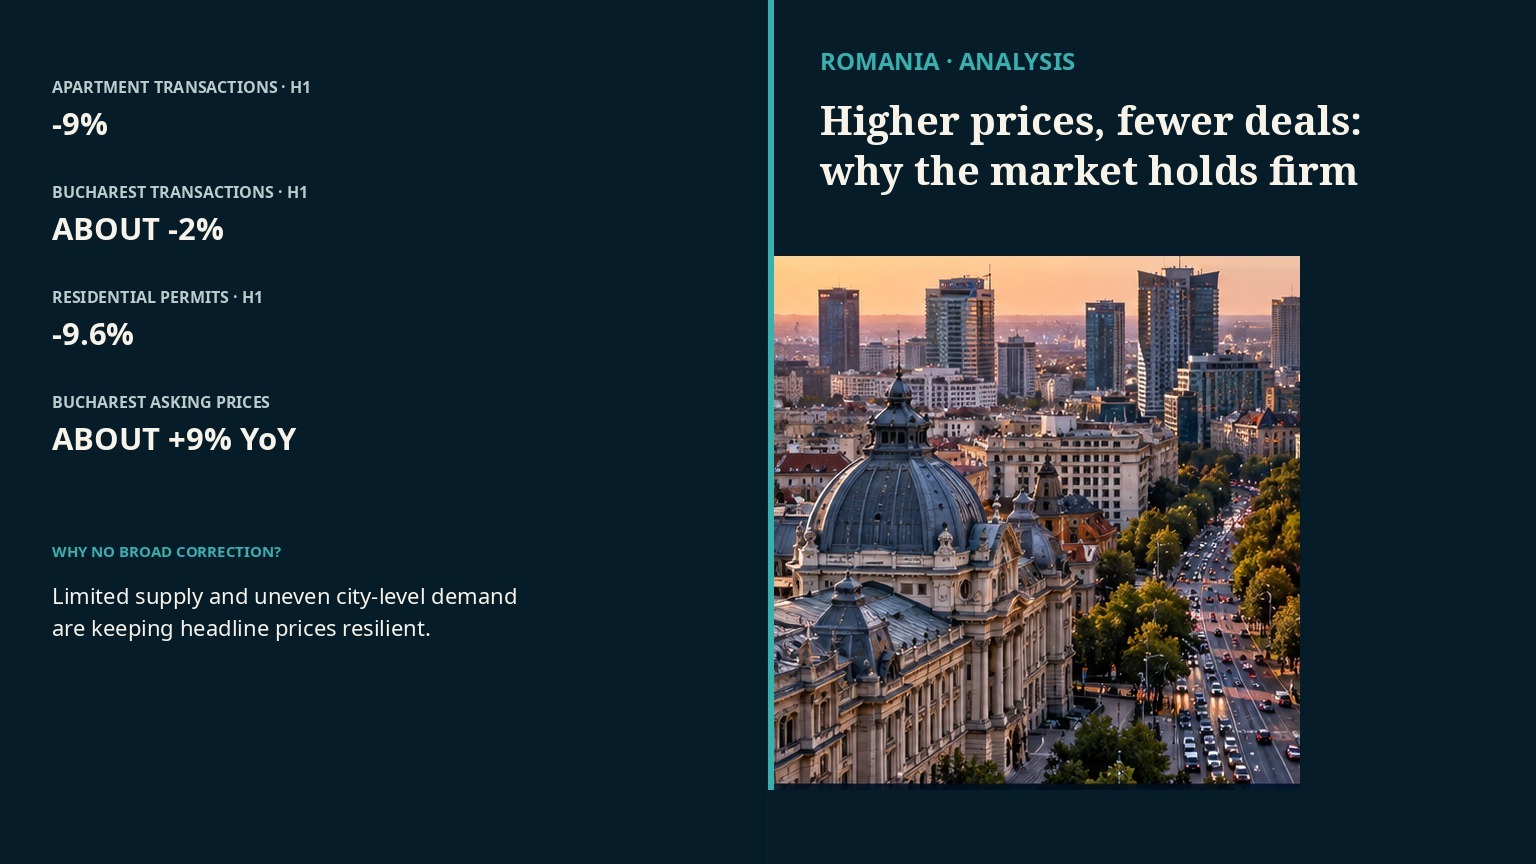
The headline looks contradictory only if prices and transaction volume are expected to move together. Colliers' September review shows that Romania sold about 9% fewer apartments in the first half than a year earlier, while Bucharest was down only around 2%. Cluj-Napoca fell about 16% and Iași 11%, while Timișoara increased roughly 3%. This is not one national market cooling at one speed.
Prices have been more resistant. Colliers says asking prices in Bucharest were roughly 9% higher year on year by mid-summer, with a similar national direction, although monthly increases had slowed. That is an asking-price measure rather than a closed-transaction price index, so it should not be read as proof that every seller achieved 9% more. It does show that weaker turnover has not yet forced a broad repricing.
Supply helps explain why. Romania completed only about 59,000 homes in 2025, the lowest level since 2017 according to the same market review. Official INS data then show 15,939 residential building permits in the first half of 2026, 9.6% fewer than a year earlier. June alone was down 15.5% year on year in permit count.
Bucharest is the exception inside that national story. The number of permits in the Bucharest-Ilfov region was slightly higher in the first half, and Colliers says the authorised net residential floor area in Bucharest was 3.6 times the year-earlier level in the first five months. That does not create apartments immediately; it points to a potential supply response over the next two to five years.
The result is a market where sellers still have some protection from scarcity, but buyers are becoming more selective. Colliers reports more project-by-project negotiation, discounts and commercial packages where positioning is weak. That is an important distinction: a market can avoid a headline price fall while still becoming much tougher for individual projects.
For an investor, the main question is therefore not whether 'Romania is rising or falling'. It is which city and which supply cycle an asset sits in. Bucharest may be building a larger future pipeline while Cluj and Iași are seeing much steeper transaction declines. Estate Briefing's Romania market guide puts those city differences, taxes and price levels in a broader framework.
Sources and limits

Colliers Romania ↗
Institutional market research · 2026-09-08
Institutul Național de Statistică via AGERPRES ↗
Official statistics release · 2026-07-31
ANCPI via AGERPRES ↗
Official transaction statistics · 2026-07-03

Eurostat ↗
Official EU statistics · 2026-07-02
This is research, not investment, tax or legal advice. Definitions and observation dates remain attached to every claim.