
Georgia’s Ministry of Finance clarified an important distinction in Public Ruling No. 143, dated 14 May 2026 and amended by No. 175 on 8 June. A qualifying residential apartment or house sold by an individual is generally subject to a 5% tax on the gain when no exemption applies; a gain from a home held for more than two years may be exempt. But a room functioning inside hotel infrastructure is not automatically treated as a residential home for this purpose, even if a sales brochure calls it an apartment.
The ruling examines an asset’s actual function as well as its registry entry. A residential unit should be independently identifiable and registered, intended for living, capable of basic utility connections and not an inseparable part of another non-residential operation. A dwelling under construction may still qualify if the project and transferred rights meet the criteria. By contrast, selling rights under a preliminary purchase agreement is a disposal of a right, not necessarily a completed residential property sale.
The general individual income-tax rate is 20% for taxable gains on other assets unless a specific exemption applies. An exemption for assets held more than two years can depend on whether the asset was used in economic activity. For illustration only, a taxable gain of GEL 50,000 would produce GEL 2,500 at 5% or GEL 10,000 at 20%, a GEL 7,500 difference. These are arithmetic examples, not an assessment of any buyer’s liability. Purchase and documented improvement costs, ownership dates, use and other circumstances matter.
Amendment No. 175 also clarifies that merely owning multiple homes, holding them for a long time or later selling them is not by itself sufficient to classify activity as systematic entrepreneurship. Before buying a hotel-format unit or reselling an unfinished property, obtain the registry extract, contract and written tax analysis for the exact transaction. homeradar.ge’s discussion of developer sales versus resale in Batumi illustrates why the right transferred can matter as much as the advertised price.
Related research: HomeRadar — developer versus resale in Batumi
Sources and limits
Georgian Ministry of Finance — Public Ruling No. 143 ↗
Official tax ruling · 2026-05-14
Georgian Ministry of Finance — Public Ruling No. 175 amendment ↗
Official amendment · 2026-06-08
HomeRadar Insights — aparthotel versus residential property contracts ↗
Independent contextual analysis; review date · 2026-10-21
HomeRadar Insights — developer versus resale property rights ↗
Independent market context; review date · 2026-10-21

National Agency of Public Registry — immovable property registration services ↗
Official registry guidance; access date · 2026-10-25
This is research, not investment, tax or legal advice. Definitions and observation dates remain attached to every claim.
 Poland · Poland unveils public housing investment map as ministry reports PLN 7.1bn in support
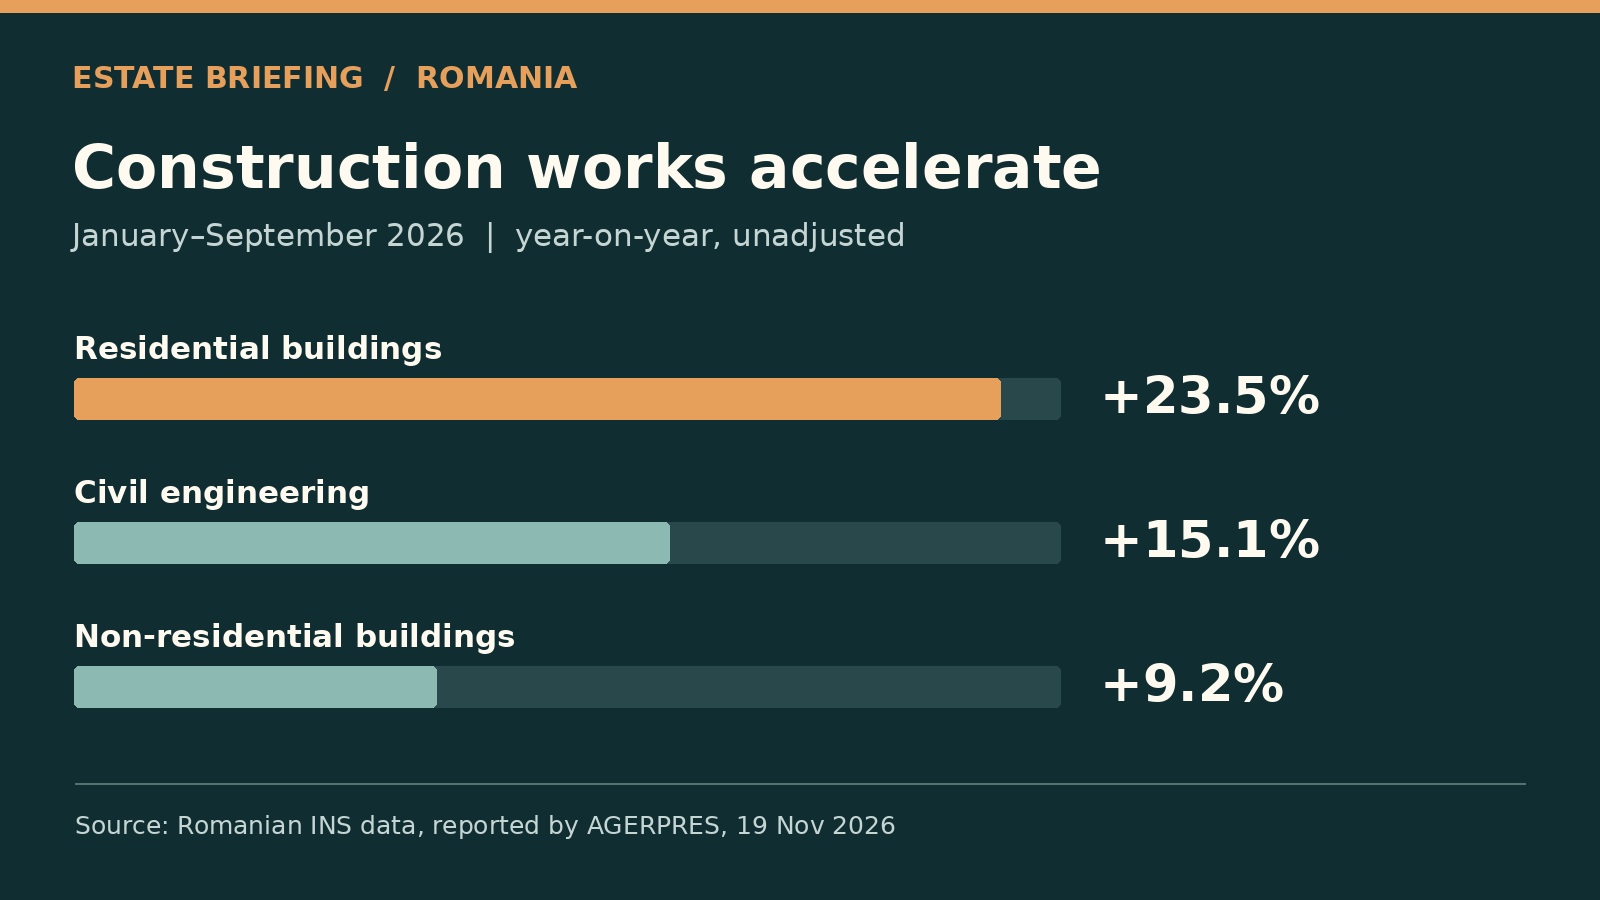 Romania · Romanian residential construction rises 23.5% in nine months
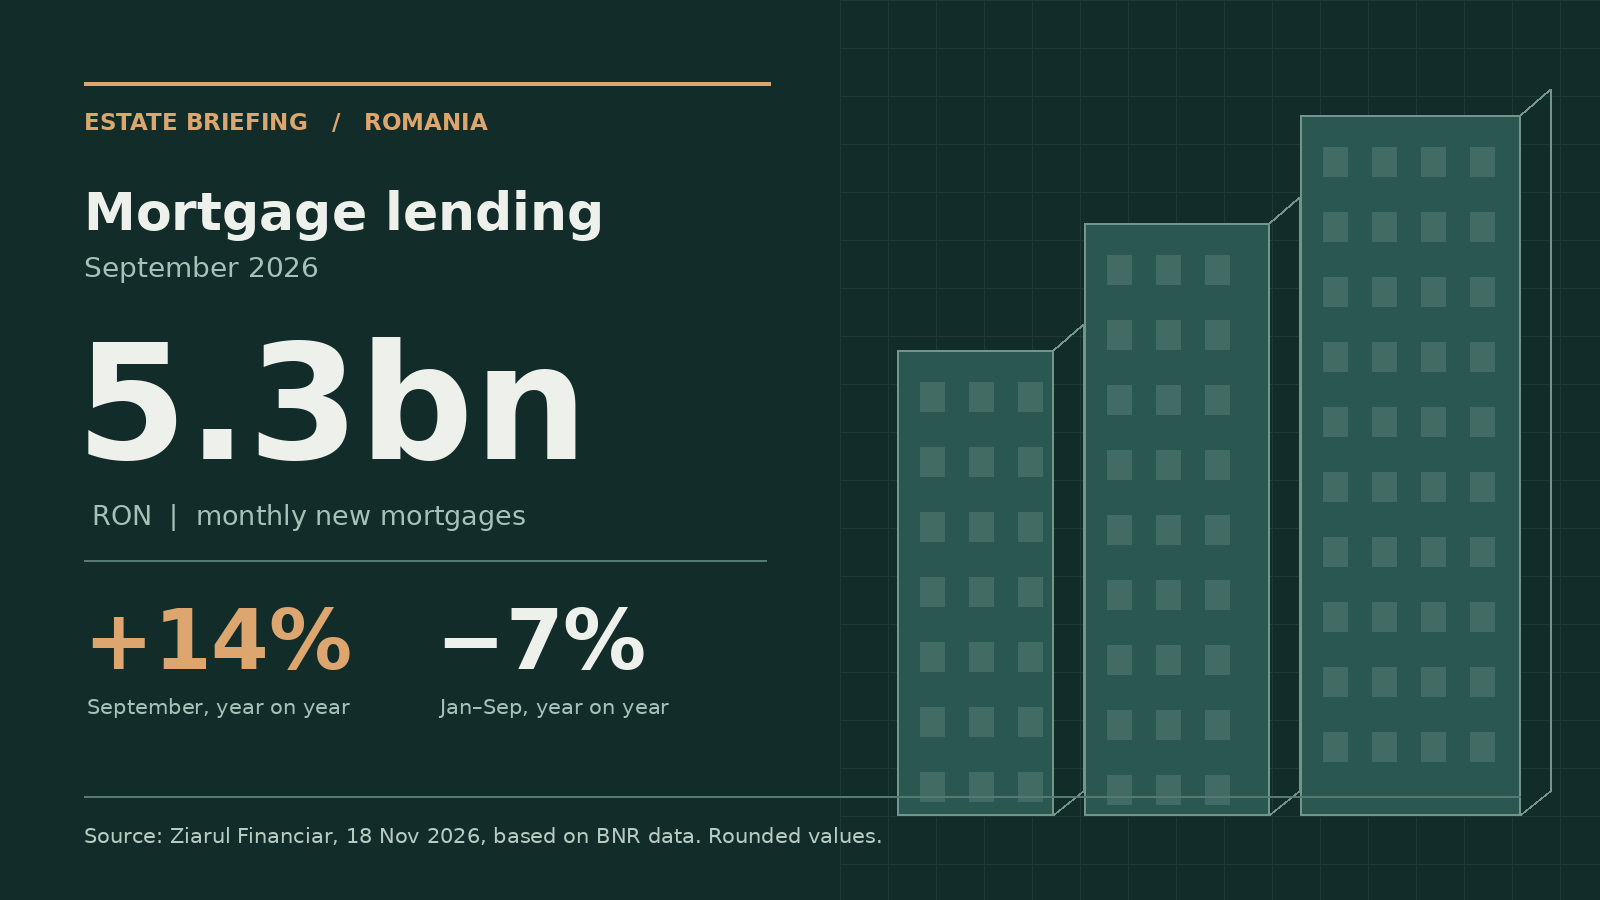 Romania · Romania’s September mortgage lending reaches a record